Somewhere between 25 and 40% of your orders are probably going through Afterpay or Zip right now. On every one of them, you are handing over 4 to 6% plus around 30 cents, against the 1 to 2% you pay on a normal card transaction.
Ask most Aussie founders why BNPL is on their store and the honest answer is “everyone has it”. It went on in 2021, it has never been reviewed, and nobody has checked whether the fees are buying incremental sales or just taxing orders that would have happened anyway.
That question got sharper in the last year. Since 10 June 2025, BNPL providers are regulated as credit under the National Consumer Credit Protection Act. They now need an Australian credit licence and have to run responsible lending checks on customers. The sign-up friction, the provider economics and the customer mix are all shifting under your feet.
With 41% of Australians using BNPL in the past six months, ripping it out on a hunch is as lazy as leaving it on autopilot. This playbook is the 5-part system for working out what BNPL actually costs you, what it actually buys you, and how to make it earn its keep.
Part 1: Work Out What BNPL Actually Costs You (It Is Not Just the Fee)
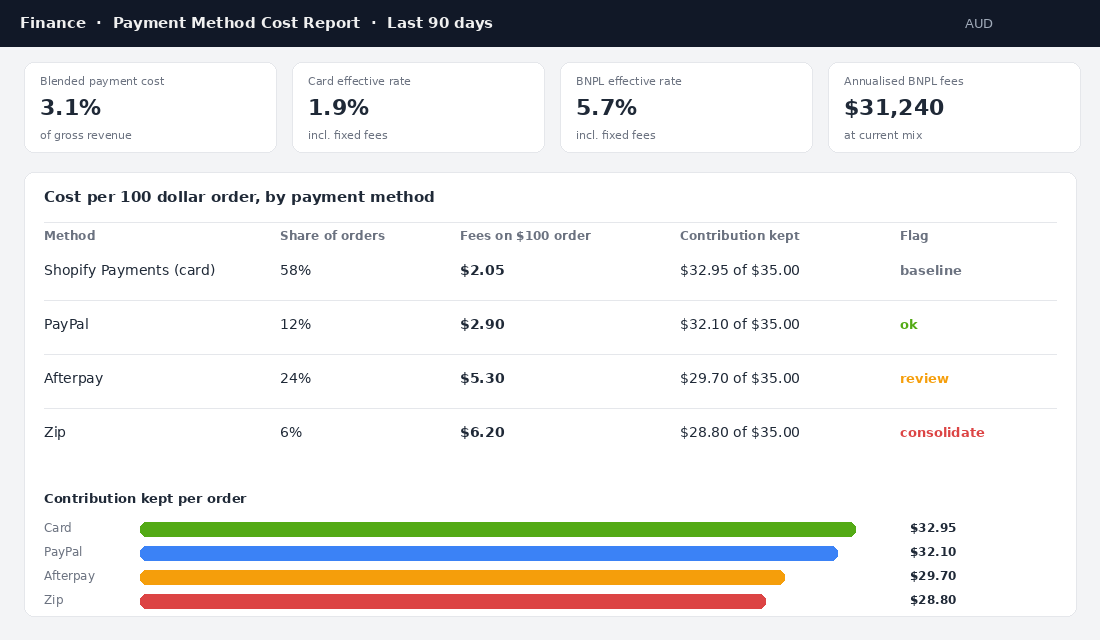
Start with the raw maths on a typical order. Say your AOV is 100 dollars and your contribution margin after product, freight and pick-pack is 35 dollars.
- Card via Shopify Payments: roughly 1.75% plus 30 cents. Cost about 2.05. You keep about 32.95 of contribution.
- BNPL at 5% plus 30 cents: cost 5.30. You keep about 29.70. That single payment choice just took 10% of the contribution on the order.
- BNPL at 6% on a discounted sale order: stack a 20% promo with the fee and a marginal order can drop below breakeven without anyone noticing.
Afterpay merchant fees in Australia typically land between 4 and 6% plus a fixed per-transaction fee, with newer and lower-volume merchants paying the top of that range. Zip and PayPal Pay in 4 sit in similar territory. None of this is secret, but almost nobody multiplies it out across a year.
Do that multiplication now. If you do 2 million dollars a year and 30% of it runs through BNPL at an average 5.2% all-in, you are paying roughly 31,000 dollars a year for the channel. That is a part-time hire, or your whole Klaviyo and app stack.
The question is never “is BNPL expensive”. It is “does it return more than it costs”. The rest of this playbook answers that.
Part 2: Work Out What BNPL Actually Buys You
BNPL providers sell three benefits: higher conversion, higher AOV and new customers. All three are real for some stores and imaginary for others. Your job is to find out which one you are.
The demand is not in question. Finder’s tracking has BNPL usage above 40% of Australians for five years running, and it skews hard to the customers most DTC brands chase: 59% of Gen Y and 57% of Gen Z have used it, against 30% of Gen X and 15% of boomers. Afterpay alone counts around 3.5 million active local users, and about 38% of Aussie BNPL users name it as their service. The category is still growing too, with Australian BNPL payments forecast to reach roughly 18 billion US dollars in 2026, up 17.5% on the year before.
Whether that demand is incremental for your store depends on three things:
- Price point. BNPL pulls hardest between roughly 80 and 400 dollars, where splitting into four makes a real difference to a pay-cycle budget. Under 40 dollars it changes almost nothing except your fees.
- Audience age. If your buyer is a 24-year-old fashion or beauty customer, BNPL is close to table stakes. If you sell to 55-year-olds, the 15% usage rate tells you how much you should pay for the privilege.
- Category habit. Fashion, beauty, sneakers and homewares are BNPL-native categories in Australia. Big retailers lean in for a reason: providers compete openly for partnerships with the likes of Myer and JB Hi-Fi because instalments demonstrably move units in those aisles.
The test that settles it is simple: measure, do not survey. Pull 90 days of orders and compare BNPL orders against card orders on AOV, discount usage, new-customer share and 90-day repeat rate. If BNPL orders carry a meaningfully higher AOV and a higher share of first-time customers, the channel is doing real work. If they look identical to card orders, you are paying a 3-point premium for money you were getting anyway.
Part 3: The June 2025 Rule Change (and Why It Matters to Merchants)
From 10 June 2025, BNPL contracts fall under the National Credit Code. Providers need an Australian credit licence, must belong to AFCA, and must run responsible lending checks before opening accounts or lifting limits.
You do not need a licence to accept BNPL, but the change lands on your store in three ways:
- New-customer friction moved to signup. A first-time BNPL user now goes through income and expense checks before their first purchase completes. Expect slightly fewer impulse first orders through BNPL, especially on cheap items, and do not panic when you see it in the data.
- The provider field is consolidating. Licensing costs money, so smaller providers are exiting or merging. Running three BNPL options at checkout made sense in 2022. In 2026 it mostly adds checkout clutter and extra reconciliation for near-zero extra conversion.
- The fee is still yours to carry. Standard BNPL merchant agreements stop you surcharging the customer, which means the cost lives in your pricing whether you acknowledge it or not. If BNPL is 30% of volume at a 3-point premium over cards, that is roughly a 1% tax on total revenue that your margins have to absorb. Price for it deliberately, the same way we handle rising costs in the price increase playbook.
The regulation is not a reason to drop BNPL. It is a reason to stop treating it as furniture. A regulated, consolidated BNPL market is one where you should be intentional about which provider you run and what you pay them.
Part 4: Run the BNPL Audit on Your Own Numbers
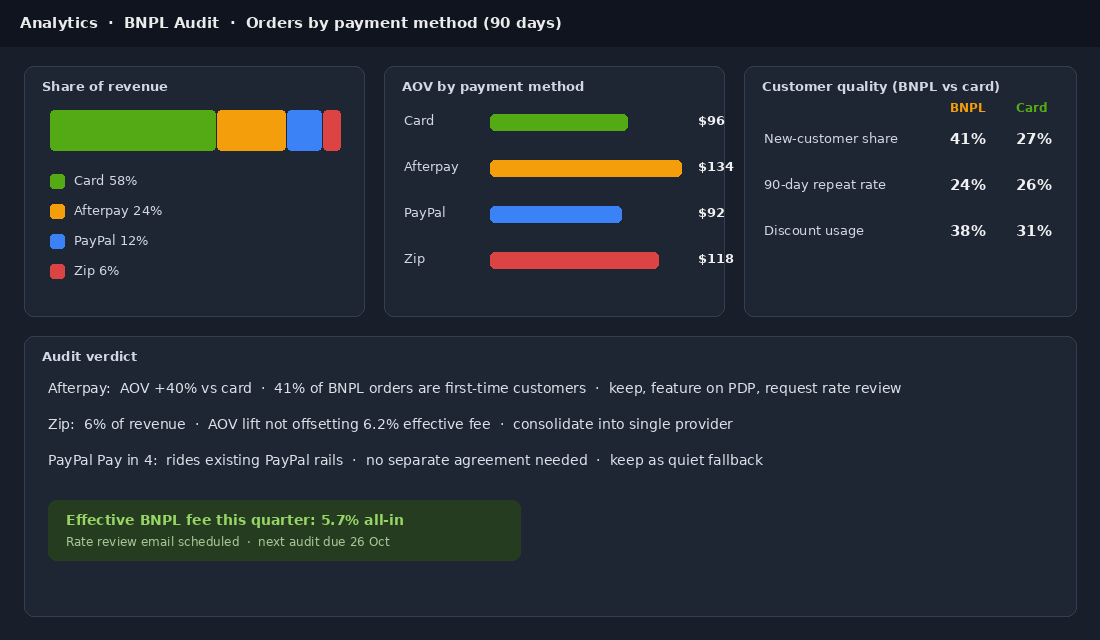
This is a 60-minute job in Shopify, and it turns the debate from opinions into a decision. Go to Analytics, then build or export a report of the last 90 days of orders with payment method attached.
Fill in five numbers for each payment method:
- Share of orders and share of revenue. BNPL below about 10% of revenue rarely justifies a second provider. Above 25% and it is core infrastructure you should negotiate on.
- AOV by method. The BNPL case usually lives here. A 96 dollar card AOV against a 134 dollar Afterpay AOV pays the fees several times over. Identical AOVs are a red flag.
- New-customer share by method. If BNPL orders skew to first-timers, the fee is part acquisition cost, and it is competing against your Meta CAC, not your card rate.
- 90-day repeat rate by method. BNPL customers who never return are being subsidised by your best customers. BNPL customers who repeat at or above card customers are simply customers.
- Effective all-in fee. Fees paid divided by BNPL revenue. Founders are routinely shocked to find the real number is 5.5 to 6% once fixed fees on small orders are counted.
Then act on what you see. If the audit says BNPL is incremental: keep it, feature it, and at meaningful volume, ask for a better rate. Merchant fees are negotiable once you are doing consistent numbers, and a half-point off 600,000 dollars of annual BNPL volume is 3,000 dollars a year for one email. If the audit says it is not incremental: cut to a single provider, pull the logos off your hero section, and keep it as a quiet checkout option while your pricing absorbs less of the cost.
Either way, rerun the audit quarterly. Payment mix drifts with your traffic sources, your price architecture and your audience age, and a decision made on 2024 data is not a decision, it is a memory.
Part 5: If You Keep It, Make It Earn Its Keep
Paying 5% for a payment method and then hiding it is the worst of both worlds. If the audit says BNPL stays, deploy it where it actually moves conversion.
The tool: Afterpay on Shopify with on-site messaging
Setup takes about half an hour:
- Apply for the merchant account at Afterpay’s business site, get approved, and note your merchant ID and secret key.
- Add it in Shopify under Settings, then Payments, then Add payment methods. Search for Afterpay, connect with your credentials, and activate.
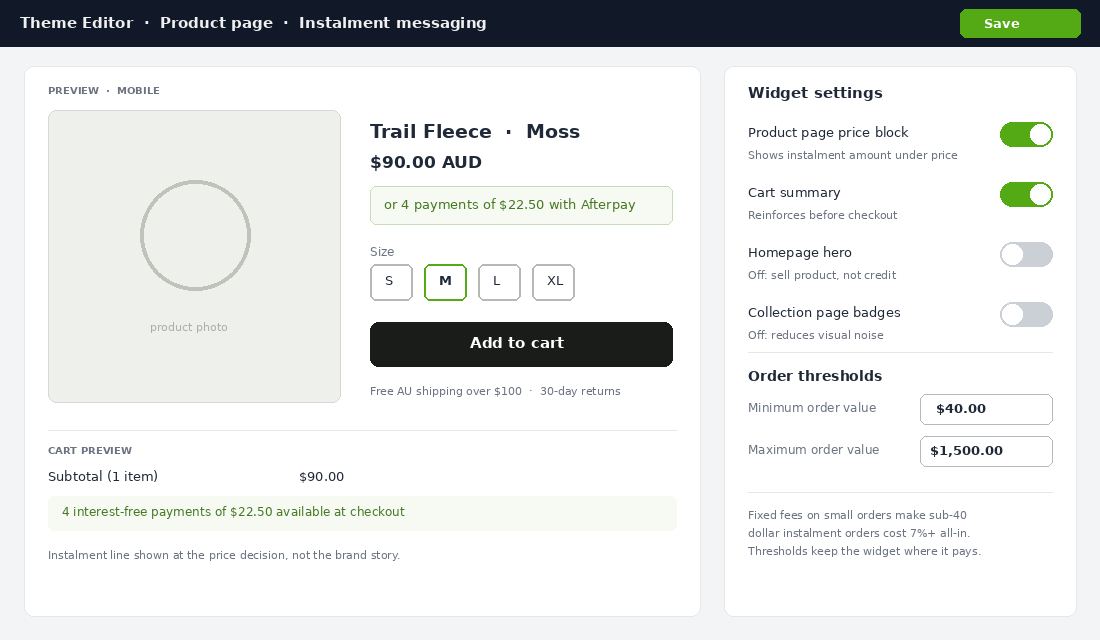
- Install the on-site messaging via the Afterpay On-Site Messaging app so product pages show the instalment line (“or 4 payments of 22.50”) near the price. This widget, not the checkout logo, is where the conversion lift comes from, because it reframes affordability while the customer is still deciding.
- Set your limits. Configure minimum and maximum order values so BNPL is not eating fixed fees on 15 dollar orders.
- Test a real transaction end to end, including the refund path, because BNPL refunds behave differently from card refunds in your reconciliation.
Then put the instalment message in the three places it pays for itself: the product page price block, the cart, and your retargeting creative for carts abandoned above your AOV. Keep it off your homepage hero. You are selling product, not credit.
And if you run BNPL, play the calendar. Afterpay Day in August is a genuine traffic event for BNPL-heavy audiences, and we covered exactly how to run it profitably in the Afterpay Day playbook. A channel you are already paying for should at least hand you its seasonal spikes.
Which provider, if you are only keeping one
For most Aussie DTC stores the shortlist is Afterpay, Zip and PayPal Pay in 4, and the decision is simpler than the sales decks make it.
- Afterpay has the biggest active Aussie user base and the strongest brand pull with under-35 fashion and beauty buyers. If your audit shows BNPL bringing new young customers, it is usually the one to keep, and Afterpay Day is a bonus traffic event you cannot get elsewhere.
- Zip reaches an audience that skews slightly older and includes shoppers who prefer an ongoing account over pay-in-4. Worth keeping only if your data shows real Zip volume you would lose, not because the logo looks reassuring.
- PayPal Pay in 4 rides inside your existing PayPal integration at rates close to your normal PayPal fees. If your BNPL share is modest, this is the cheap way to keep an instalment option on the table without a second merchant agreement.
What almost never makes sense in 2026 is running all three. Pick the one your customers actually use, let the others go, and bank the simpler reconciliation as a bonus.
Worked Example: The BNPL Audit on a $1.2M Activewear Store
Numbers make this real. Imagine you run a Melbourne activewear brand doing 1.2 million dollars a year, with a 38% contribution margin after product, freight and pick-pack. You pull 90 days of orders and the audit comes back like this:
- Share: BNPL is 32% of revenue, or roughly 384,000 dollars a year. Afterpay carries 88% of it, Zip 12%.
- Cost: effective all-in BNPL fee of 5.6%, about 21,500 dollars a year. The same revenue on cards at a 1.9% effective rate would cost about 7,300 dollars. The BNPL premium is roughly 14,200 dollars.
- AOV: 142 dollars on BNPL against 104 dollars on cards.
- New customers: 61% of BNPL orders are first-timers, against 44% on cards.
- Repeat: 19% of BNPL customers reorder within 90 days, against 24% on cards.
Now the judgement call. Even if only a quarter of that BNPL revenue is truly incremental, that is about 96,000 dollars of extra sales at 38% contribution, or roughly 36,500 dollars of contribution. That comfortably covers the 14,200 dollar premium. BNPL stays.
But the audit also says three other things. Zip is carrying too little volume to justify a second agreement and reconciliation, so it goes. The lower repeat rate means BNPL first-timers need a stronger post-purchase flow, not a bigger welcome discount. And with a third of revenue on Afterpay, this store should be sending a rate review email this quarter. Half a point off 338,000 dollars of Afterpay volume is about 1,700 dollars a year for one conversation.
What the 1 October 2026 Surcharge Ban Does to the BNPL Maths
From 1 October 2026, eftpos, Mastercard and Visa ban surcharging on credit, debit and prepaid cards, and the Reserve Bank paired that with lower interchange on card payments. Two things follow for BNPL.
First, card acceptance is getting slightly cheaper, which widens the gap between your card rate and your BNPL rate. A 3-point premium can quietly become a 3.5-point premium without anything changing on the BNPL side. Rerun Part 4 in October with the new card rate, not last year’s.
Second, stores that used a card surcharge to offset overall payment costs have lost that option, so the true cost of every payment method now lands in your pricing. BNPL surcharges were already off the table under most merchant agreements. Our surcharge ban playbook covers how to absorb, reprice or re-route the lost fee, and it is worth reading alongside the earlier BNPL margin test before you set your BFCM promo floors.
The Four Mistakes Founders Make With BNPL
- Judging it by revenue share instead of incrementality. “BNPL is 30% of our sales” proves nothing. The question is how many of those orders would have happened on a card. AOV, new-customer share and repeat rate are the tells, not the share number.
- Stacking BNPL fees on top of deep discounts. A 25% off sale order paid through BNPL at 6% all-in can quietly land below breakeven on marginal SKUs. Set your promo floor with the payment fee included, not as an afterthought.
- Leading the brand with credit. Stores that plaster instalment logos across the hero teach customers to see the brand as a payment plan. Keep the message at the price decision, where it converts, and out of your brand story, where it cheapens.
- Never asking for a better rate. Providers publish rack rates and negotiate real ones. If you have two years of volume history and BNPL above a quarter of revenue, you have bargaining power. Silence is the most expensive setting.
None of these mistakes require removing BNPL to fix. They require treating it like any other supplier: measured, priced in, and renegotiated when the volume justifies it.
The Compound Effect: Payment Mix Is a Profit Lever, Not Plumbing
Here is the shift that matters. Most founders treat the payments page as set-and-forget plumbing. The operators who run this audit treat payment mix the way they treat shipping rates and supplier terms: a line item that gets reviewed, negotiated and priced into the product every quarter.
The compounding is quiet but real. A store doing 2 million a year that trims its blended payment cost by half a percent banks 10,000 dollars, every year, with no extra traffic. Add the AOV lift from putting instalment messaging where it works, minus the fee drag from orders where it does not, and payment mix starts behaving like a conversion project with a permanent payoff. It also feeds straight into your cash position, which is why we treat it as a sibling of the systems in our cash flow management guide and the checkout optimisation playbook.
Nobody brags about their payment mix at a founder dinner. They brag about net margin, and this is one of the few levers that moves it without touching product, traffic or team.
Your BNPL Decision Checklist
Steal this. Run it this week, then every quarter.
- Cost: effective all-in BNPL fee calculated (fees paid divided by BNPL revenue), compared against your card rate.
- Share: BNPL share of orders and revenue for the last 90 days, trend noted against the prior quarter.
- Lift: AOV, new-customer share and 90-day repeat rate compared between BNPL and card orders.
- Verdict: incremental (keep and feature), marginal (keep one provider, quiet placement), or not incremental (single provider, pricing adjusted, review again next quarter).
- Rate: if BNPL exceeds 25% of revenue, a rate review email sent to your provider this quarter.
- Placement: instalment messaging on PDP price block and cart, off the homepage hero, thresholds set to block sub-40-dollar BNPL orders.
- Compliance reality check: no surcharging in breach of your merchant agreement, pricing reviewed so the fee is absorbed deliberately.
- Calendar: Afterpay Day and BFCM plans account for the fee in promo maths before the discount is set.
The founders who get this right are not pro-BNPL or anti-BNPL. They are pro-arithmetic. Run the numbers, make the call, and put the decision on a quarterly repeat.
Inside eCommerce Circle, profit architecture is one of the core pillars we work on with every member, and payment mix is a standing item in the workshop for exactly this reason. We have helped hundreds of Aussie Shopify founders find margin hiding in plain sight. If you want a second opinion on your BNPL numbers, let’s talk.